Indexed universal life insurance
Build a legacy for them.Build financial options for you.
Discover how Index Universal Life combines family protection with cash-value potential.
Offer not available in New York, New Jersey, or Pennsylvania.
The first step is a short questionnaire. No obligation to apply.
15 minutes
A weekday phone call
Eastern time
You pick an open slot
No obligation
You decide whether to apply
Reserve your review
Choose a time that works for you.
A 15-minute phone conversation. Weekdays only. All times are Eastern.
Everglade Legacy Advisors
15-minute phone review
Eastern
Pick an open weekday. The time is saved on the office calendar. No obligation to apply.
Leave a legacy. Build one while you are here.
The legacy you leave behind is a death benefit for the people you love. Cash value is the part you can build for the years you are still living.
A death benefit for the people you love.
Help with household bills if you die while the policy is in force.
Cash value that may accumulate.
A feature to understand as you plan the years ahead.
A qualifying terminal-illness benefit.
Early access to part of the death benefit on eligible policies.
Three reasons to look at one policy.
The death benefit is there for the people who would keep the household going. Cash value may accumulate beside that protection. On an eligible policy, a terminal-illness benefit may help with bills while you are living. Each feature has a different job.
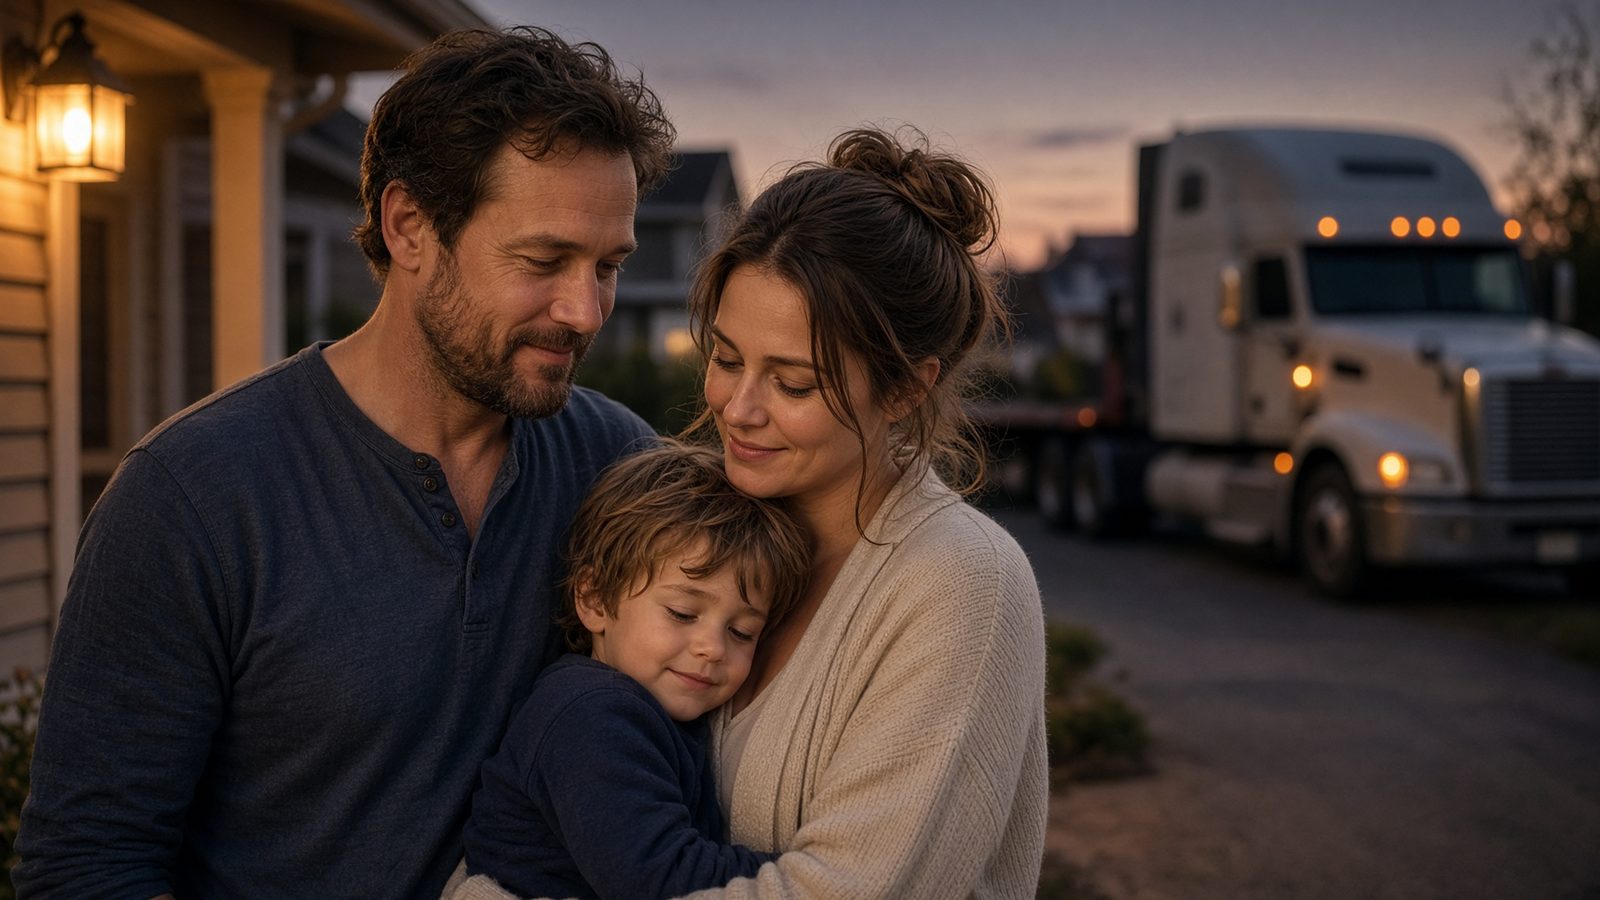
Family protection
The legacy you leave for the people who depend on you.
If you die while the policy is in force, the people you name can receive a benefit for the mortgage, everyday bills, and the life you want them to keep.
Cash-value potential
Value that may build for the years ahead.
A properly funded policy may accumulate cash value over time.
Qualifying terminal-illness benefit
Help with bills during a qualifying illness.
Some policies pay part of the death benefit after a qualifying terminal-illness diagnosis. That can help with household expenses while you are living.
What is worth bringing to the review
Who the benefit is for
The people and the household bills you want a death benefit to help with.
Whether cash value fits the timeline
It depends on what you pay in, what the policy charges, and how long the policy stays in force.
Whether a living benefit is included
Ask if the contract you are considering has a terminal-illness provision, and what using it does to the remaining benefit.
What you can understand in 15 minutes.
You complete a short questionnaire. If the office accepts it, you receive a confirmation and you can choose a time. The appointment is optional. With a licensed advisor, you can sort out who the policy is for, how the features fit together, and whether the cost belongs in the budget. No obligation to apply.
- Who you want to protect.
- How the death benefit, cash value, and any terminal-illness benefit work together.
- What the cost could mean for your budget.
- Whether to apply, or to stop.
What happens next
1
Send a short request
Answer a few questions. If delivery fails, your answers stay on the page so you can try again.
2
Book only if you want to
After the office accepts the request, you can choose a 15-minute weekday phone call. Booking is optional.
3
Leave with a clear next step
Simon explains costs, limitations, and whether the policy is worth exploring. A request is not an application.
About Simon
A conversation with a real person.
Hi, I'm Simon. My goal is to help families create a legacy they can be proud of, protecting the people they love and building generational wealth.
When I'm not helping a family build a legacy, I'm outside with my dogs, on a trail, working on my own.
Plain language
Who you want to look after comes first.
Then we talk through the coverage worth exploring.
20128364
National Producer Number
Look it up before you book.
Verify
Check the license yourself.
Verify this licenseoffice@evergladelegacyadvisors.com407-476-8216Facebook
Questions people ask first
What will we cover in the review?
Who depends on you, the bills you want coverage to help with, your budget, and whether indexed universal life is worth exploring.
How much would coverage cost?
Premiums depend on age, health, coverage amount, and the policy. Simon can discuss costs and the funding needed before you decide whether to apply.
Is indexed universal life right for everyone?
No. It involves ongoing premiums, policy charges, and a long-term funding commitment. The review is a chance to see whether those tradeoffs fit.
Is cash value guaranteed to grow?
No. Results depend on premiums, charges, and interest credits. Caps or participation rates can limit credits. Charges continue when credits are low, and too little funding can cause the policy to lapse.
What happens if cash value is used?
Loans and withdrawals reduce cash value and the death benefit. They can increase lapse risk, and taxes may apply. Ask about the specific contract before accessing funds.
What happens after I send my request?
If the office accepts it, you receive a confirmation and can choose a 15-minute weekday phone call. Booking is optional. A request is not an application and does not put coverage in force.
Make time for the future you’re building.
A short questionnaire starts the request. A 15-minute review is optional after it is accepted. No obligation to apply.