- NoBlood test
- NoMedical exam
Many applicants may qualify without a traditional medical exam, depending on age, health, carrier, and underwriting requirements.
For CDL drivers, owner-operators, and the households they support
Your income depends on you.
Shouldn’t your life insurance protect more than just what happens after you’re gone?
Learn how a properly structured policy may provide living benefits, build cash value over time, and help protect the people waiting for you back home.
Living benefits
Cash value accumulation
Family protection
Free 15-minute review · No obligation · Licensed insurance professional
The exposure
Your truck isn’t your most valuable asset. You are.
A truck creates income only when someone capable is in the seat. Mortgage or rent. Truck payments. Food. Family. Business costs. Retirement. All of it depends on income continuing.
What happens if you can’t drive?
Serious illness
Income can stop while bills do not.
Unexpected life event
Injury or time off the seat can stall everything you cover.
Death
The household still has a mortgage, food, and a future to fund.
Traditional life insurance is primarily designed to protect your family after death. Certain modern permanent policies may also provide benefits while you are still living — depending on the contract, riders, and whether you qualify.
The strategy
Life insurance can do more than leave a death benefit.
Indexed Universal Life — IUL — is permanent life insurance that can combine lifelong protection with potential cash value accumulation. Depending on how the policy is designed, funded, and kept in force, it may provide access to cash value and certain living-benefit features.
It is not right for everyone. The first step is not buying. It is seeing whether it fits.
Three things that matter
Protect today. Build for tomorrow. Take care of who is waiting at home.
Living benefits
Protection doesn’t always have to wait until death.
Depending on the policy and available riders, qualifying chronic, critical, or terminal illnesses may allow access to a portion of the death benefit while you are still alive. Terms, eligibility, and amounts vary.
Cash value accumulation
Build something for the road ahead.
A properly structured permanent policy may accumulate cash value over time. Depending on the contract, available cash value may potentially be accessed through withdrawals or policy loans for:
- Retirement
- Business opportunities
- Emergencies and major purchases
- Family needs
Loans and withdrawals reduce cash value and death benefit and can cause a lapse. Growth is not guaranteed except where the policy says so.
Family protection
Protect the people waiting for you back home.
The core job is still life insurance. A death benefit may help loved ones with mortgage or rent, household bills, debt, education, final expenses, and lost income.
Today and tomorrow
What happens when the wheels stop turning?
Someday, every driver stops driving. The question is whether the money is prepared when you do.
Today
You’re driving to provide for them.
Your income helps keep the household, bills, business, and future moving.
Tomorrow
Build toward the day you no longer have to.
A properly structured long-term financial strategy can help you prepare for life after the road.
An IUL is not right for everyone. The first step is not buying a policy. It is simply determining whether the strategy fits your goals, budget, and insurance needs.
Owner-operators
For owner-operators, the risk can be even bigger.
You may not only be supporting a household. If your ability to work suddenly changes, the consequences can reach beyond the kitchen table.
- Truck payments
- Equipment
- Business expenses
- Employees
- Operating costs
- Commercial obligations
A properly designed protection strategy can add another financial layer around what you have built — if you qualify and the numbers work.
How a review works
Three steps. No pressure. No obligation.
01
Answer a few questions
ZIP, CDL, driving type, who you protect, health, and current coverage.
02
Review your options
A licensed independent professional looks at whether an IUL — or another policy — may fit.
03
Choose what makes sense
If you qualify and it fits, you review personalized coverage and funding. If it does not, you still leave with a clearer plan.
Independent advice
You shouldn’t have to shop insurance alone.
An independent professional can compare products from multiple highly rated insurance companies rather than representing only one carrier. Not every driver will qualify. Not every IUL is the right IUL. Sometimes term or another design is the honest answer.
- Compare products from multiple highly rated carriers
- Personalized design around your miles and household
- Honest talk about affordability and alternatives
- If an IUL is not a fit, you hear that too
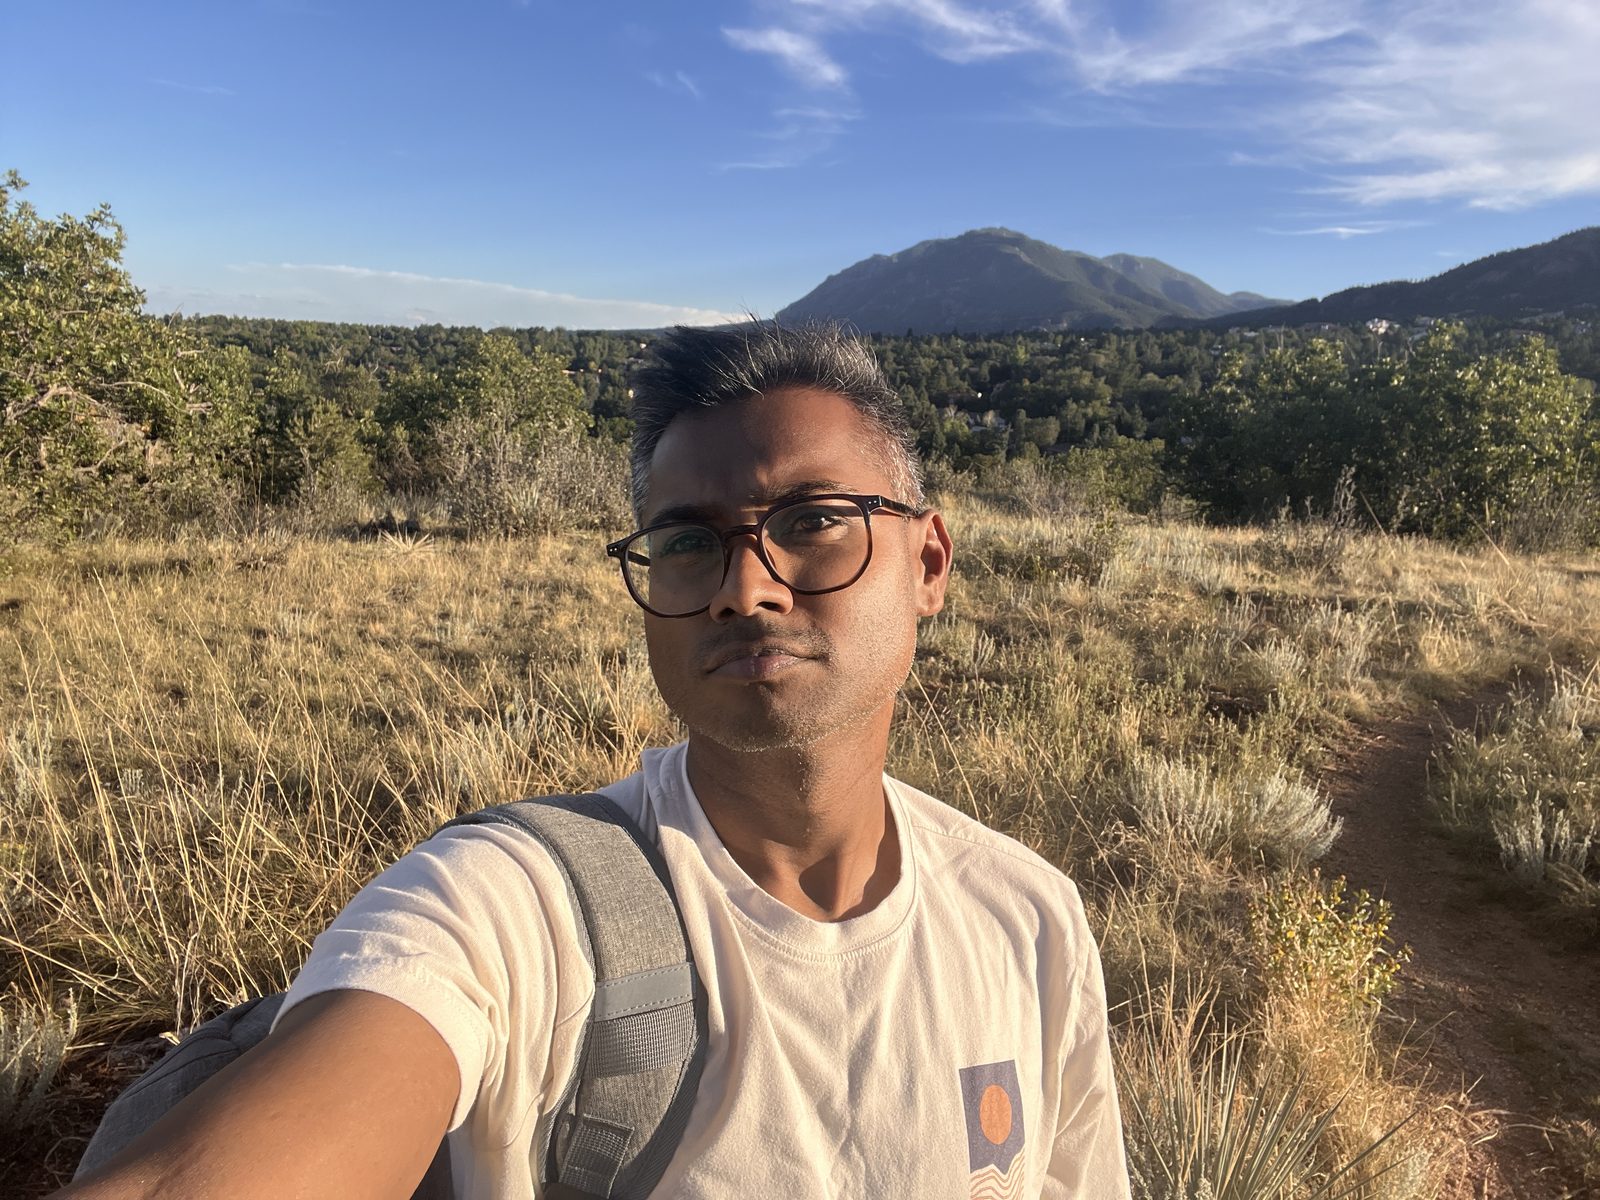
Licensed life insurance professional
Simon Pullay
Independent insurance professional · Everglade Legacy Advisors
5+ years of insurance experience
Additional states may be supported through appropriately licensed partners.
Independent life insurance professional helping CDL drivers and owner-operators look at living benefits, cash value potential, and family protection — without a sales-floor pitch. If an IUL is not the right tool, you will hear that on the call.
Your answers are used to prepare a licensed review. They are not a public application and not a guarantee of coverage.
Questions drivers actually ask
Straight answers. Then a real review.
Indexed Universal Life is a type of permanent life insurance. It can combine a death benefit with the potential to accumulate cash value. Interest credited to cash value is typically linked to a market index, subject to the policy’s caps, participation rates, spreads, and charges. An IUL does not invest directly in the stock market.
The road takes care of today. Make sure you’re building for tomorrow.
You’ve spent years working to provide for the people who depend on you. Take a few minutes to see whether an Indexed Universal Life policy or another life insurance strategy may fit your goals. No pressure. No obligation. Just a clear review of your options.
Free 15-minute review · No obligation · Licensed insurance professional