Mortgage protection life insurance
Don’t let a remaining mortgage threaten the roof over their heads.
Coverage designed so a spouse or children are not left with the house payment if you die.
Term, cash-back term, or permanent — matched to the loan you actually have. No medical exam on many plans.
Pay off the home
Protect the people in it
No medical exam on many plans
Free 15-minute review · No obligation · Licensed insurance professional
Why this exists
The house is often the biggest bill a family still has after a funeral.
Life insurance does not replace you. It can replace the payment that would otherwise land on a spouse, a child, or whoever is left in the house. If you have a mortgage and people who live there, this is the conversation.
Why mortgage protection
Four reasons families look at this.
Pay off the house
A lump-sum death benefit is meant to help pay the remaining mortgage so a spouse or children are not forced to sell.
Protect the people in it
The policy is for the household that would still have the payment if your income stopped.
Premiums designed to stay level
Many mortgage-protection designs lock in a rate for the term you choose — so the payment is not a moving target.
No medical exam on many plans
A lot of applicants answer health questions instead of a physical. That is not a guarantee of coverage or of day-one full benefits.
- NoBlood test
- NoMedical exam
How it works
A death benefit for the mortgage — with living-benefit riders on some contracts.
Mortgage protection is life insurance. The base policy pays if you die. Some carriers add riders that let you access part of the benefit while you are living, if a qualifying illness or chronic-care definition is met.
Death benefit
Paid to the beneficiary you name. They can use it for the mortgage, or other bills. The lender is not paid automatically unless you assign the policy.
Critical illness rider
Some contracts let you accelerate part of the death benefit after a qualifying event such as a heart attack, stroke, or cancer — if the rider is on the policy and the definition is met.
Chronic illness / disability rider
Some contracts allow an acceleration if you cannot perform a set number of activities of daily living. This is not a standalone disability policy. Rider language varies.
Level premiums on many designs
Term and return-of-premium designs are typically built so the rate does not increase during the term if you pay on time.
Free 15-minute review · No obligation · Licensed insurance professional
Coverage options
Match the policy to the loan — not the other way around.
Straightforward term, cash-back term if you want premiums back if you outlive it, or permanent coverage if you want protection after the house is paid off.
Term coverage
10, 15, 20, 25, or 30 years. Often the most affordable way to match the remaining loan.
Cash-back / return of premium
If you outlive the term and the policy stays in force, some contracts return the premiums you paid. Not interest. Not a savings account. Higher cost than plain term.
Permanent coverage
Whole life or IUL if you want coverage that can last beyond the mortgage and may build cash value. A different product than a simple mortgage-term policy.
Advisor
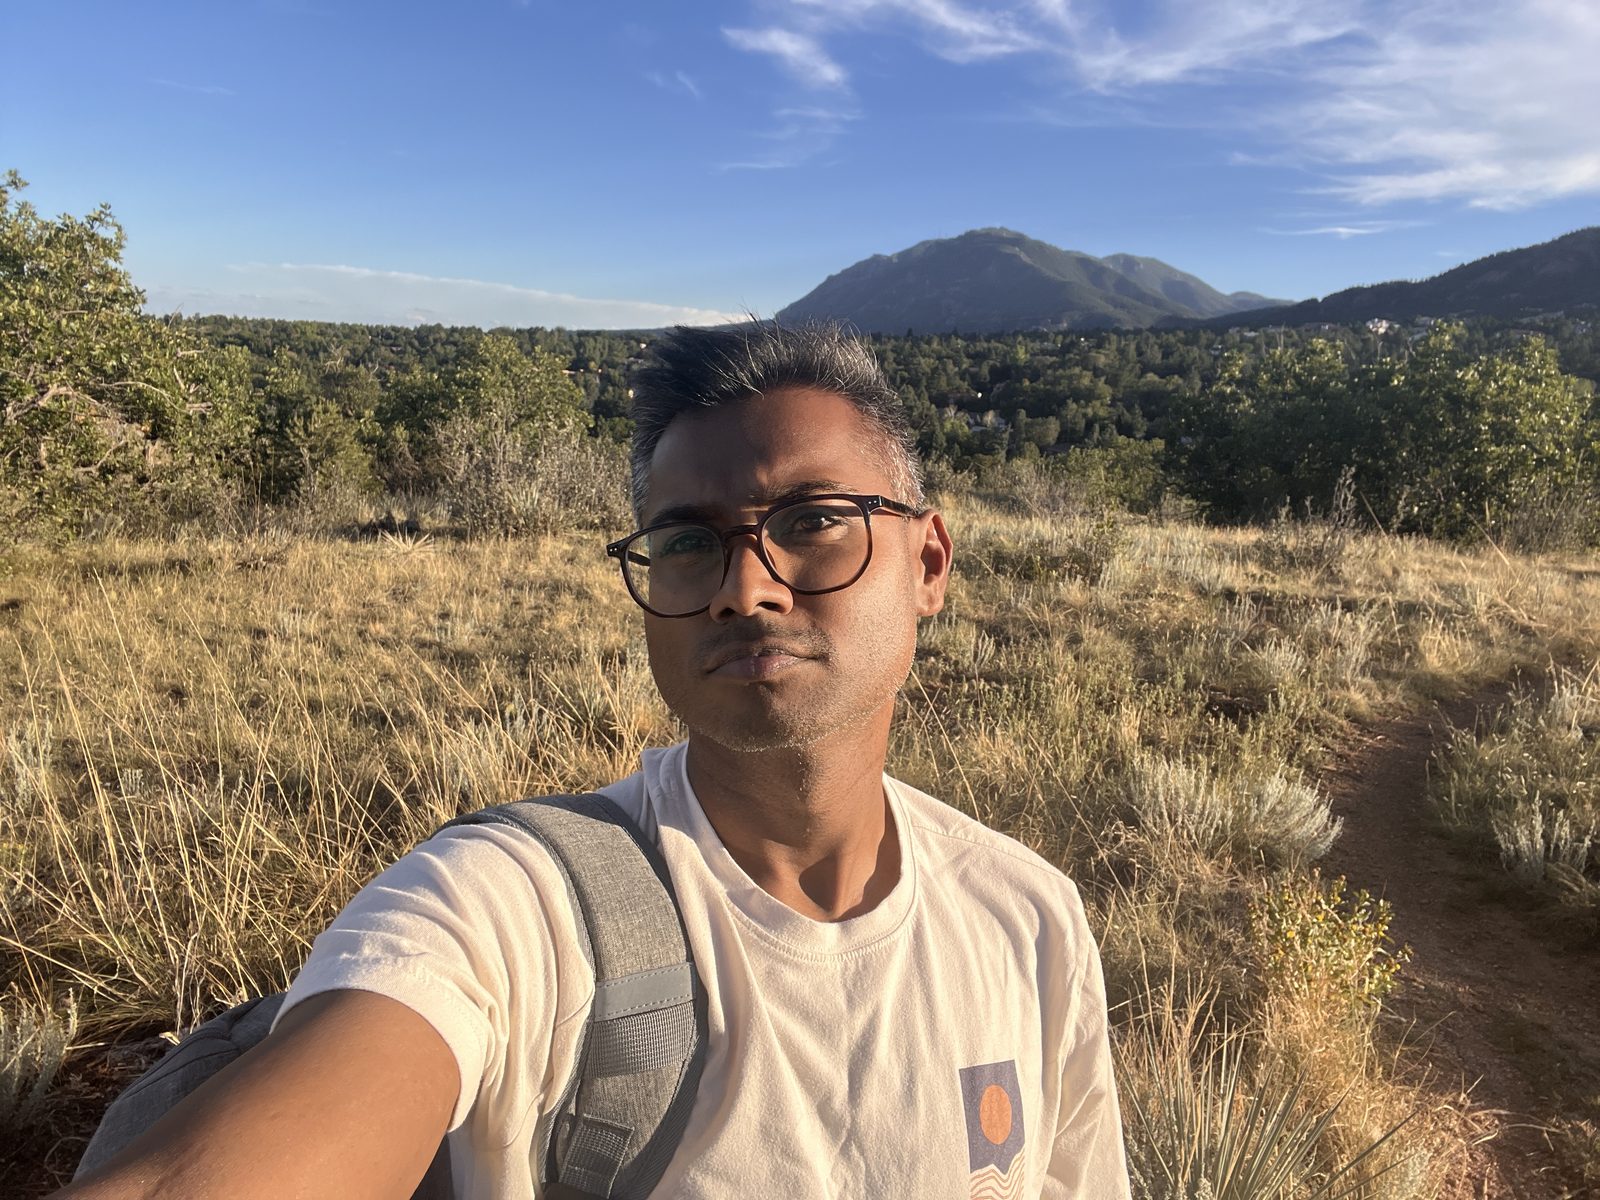
Simon Pullay
Independent insurance professional · Everglade Legacy Advisors · NPN 20128364
I compare term, return-of-premium, and permanent designs from multiple highly rated carriers. If the mortgage does not need a policy, I will say so on the call.
Free 15-minute review · No obligation
FAQ
Straight answers.
Usually no. The death benefit is paid to the beneficiary you name. They can pay off or pay down the loan. A policy can be assigned to a lender — we will tell you if that is even useful.
Ready to protect your biggest investment?
See if you qualify. Then pick a time. I’ll show you term, cash-back, or permanent — only if it actually fits the loan and the budget.
Free 15-minute review · No obligation · Licensed insurance professional