For yourself
Lock in a plan while you can still qualify.
Ages in the typical window (often 50–85) with a budget for a small monthly premium.
Final expense coverage
A small whole life policy built to help cover burial, cremation, and last expenses.
No medical exam on many plans. Premiums designed to stay level. Coverage that can last a lifetime if premiums are paid.
No medical exam on many plans
Premiums designed to stay level
Coverage that can last a lifetime
Free 15-minute review · No obligation · Licensed insurance professional
Many final expense plans use simplified underwriting with no traditional medical exam. Eligibility, waiting periods, and rates depend on age, health, carrier, and the contract.
The problem
A funeral, cremation, leftover medical bills, and travel for family can add up in days — not months. Without a plan, that invoice goes to a spouse, a son, or a daughter.
Social Security’s one-time death payment is small. Term policies expire. Employer coverage often ends when work ends. Final expense is meant to fill that gap.
What it is
Final expense insurance is typically a small whole life policy. The death benefit is meant for funeral, burial, medical leftovers, and other last bills. Leftover money belongs to the beneficiary you name.
It is not right for everyone. The first step is not buying. It is seeing whether you qualify, and which issue type may fit.
Why families use it
A defined amount for last bills
The death benefit is meant for funeral, burial or cremation, leftover medical bills, and whatever else the family needs to close out.
No medical exam on many plans
Most final expense policies replace a physical with a short health questionnaire — or skip health questions entirely on guaranteed-issue designs.
Premiums designed not to increase
These are typically small whole life policies. If the policy stays in force, coverage does not expire at a term date.
Three paths
We do not promise day-one full coverage for everyone. Graded and guaranteed-issue plans often pay a limited benefit if death from natural causes happens during a waiting period.
Simplified issue
Short health questions. No medical exam. Many people in fair-to-good health may receive day-one coverage if they qualify.
Modified / graded
For some health histories. A waiting period may apply for natural-cause death. Accidental death is often treated differently.
Guaranteed issue
No health questions. Acceptance in the eligible age range. A waiting period for natural-cause death is common. Highest cost per dollar of coverage.
Who it’s for
For yourself
Ages in the typical window (often 50–85) with a budget for a small monthly premium.
For a parent
The parent still needs to participate in the application. We walk that process with both of you.
How a review works
01
ZIP, who the coverage is for, age, and two health questions. About 45 seconds.
02
A licensed independent professional looks at simplified, graded, or guaranteed-issue paths — whichever may fit.
03
If you qualify and it fits the budget, you see coverage designed for funeral and last expenses. If it does not, you still leave with a clearer plan.
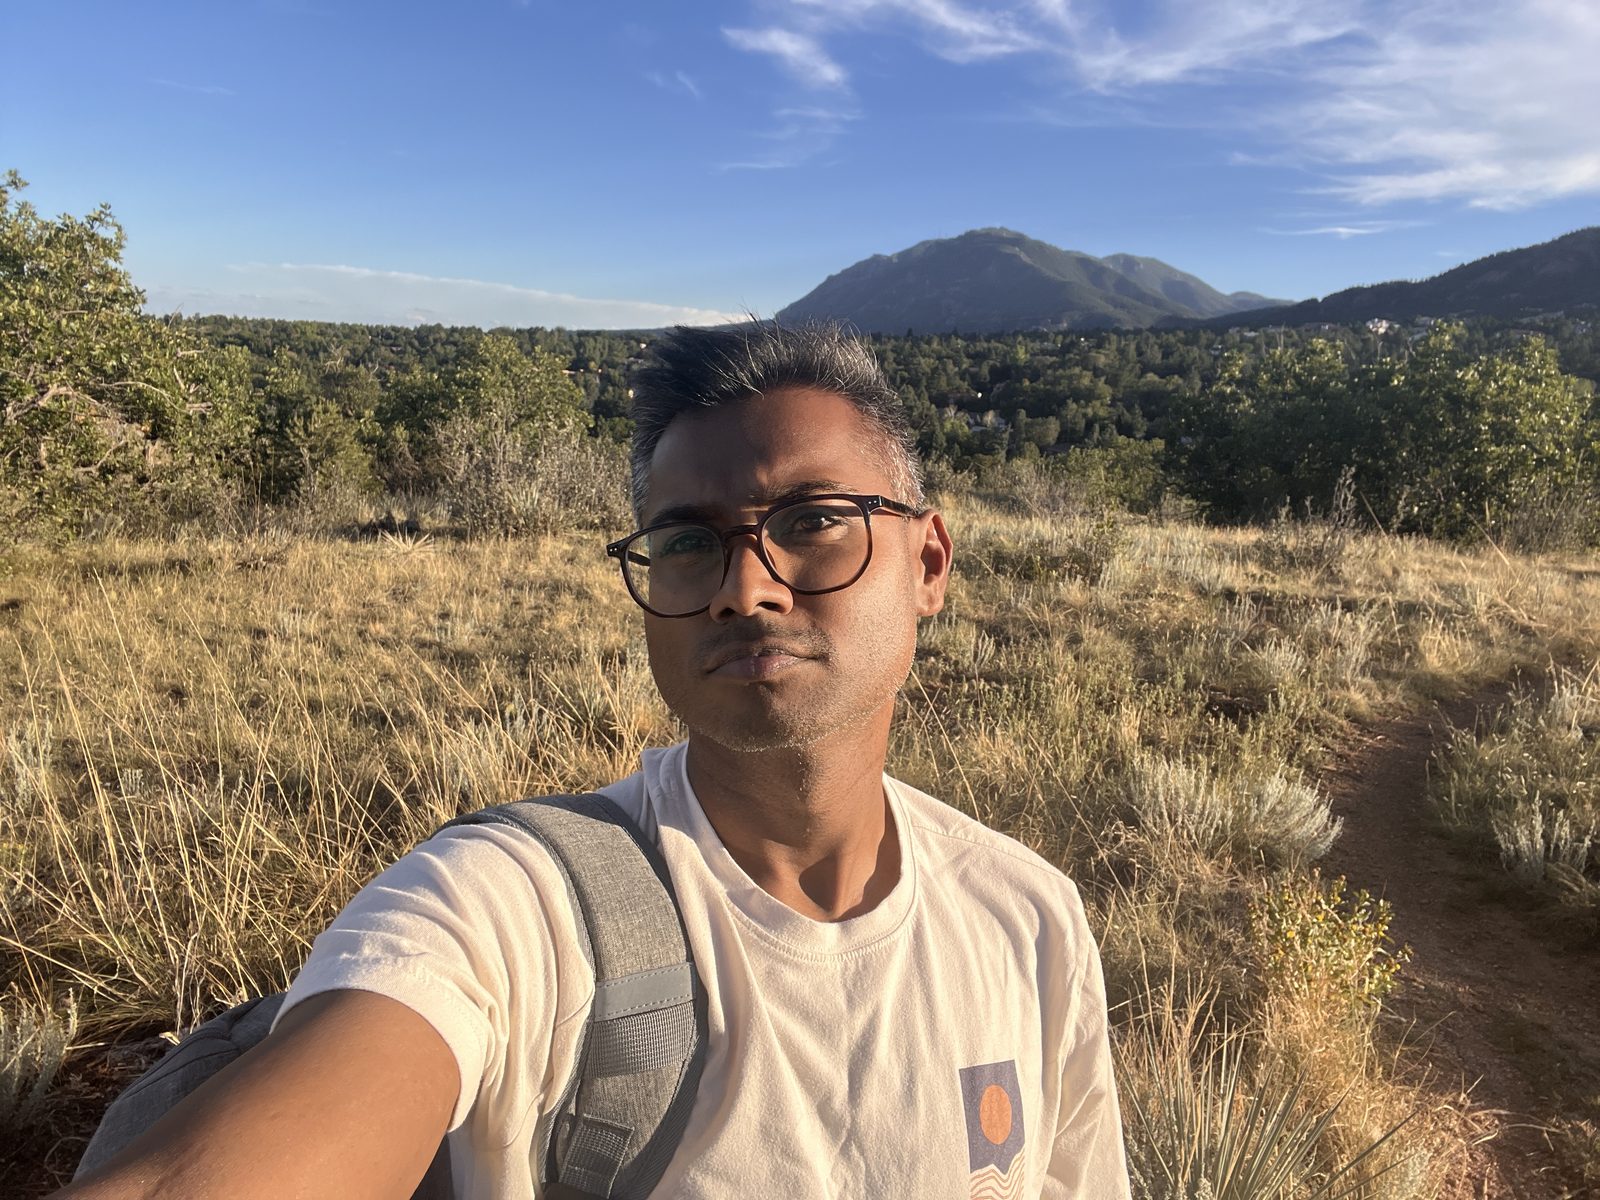
Licensed life insurance professional
Independent insurance professional · Everglade Legacy Advisors
5+ years of insurance experience
Additional states may be supported through appropriately licensed partners.
I help families see whether a final expense policy fits — and which issue type they may actually qualify for. If guaranteed-issue with a waiting period is the honest path, you hear that on the call.
Straight answers
It is a smaller permanent life insurance policy, usually whole life, designed to help with funeral, burial, cremation, and other last expenses. Leftover money goes to the beneficiary.
I’ll review options that match age, health, and budget. No pressure. No obligation. Just a clear look at whether a final expense policy belongs in the plan.
Free 15-minute review · No obligation · Licensed insurance professional