Mortgage Protection Life Insurance
The legacy you leave behind can be the home.
Life insurance planned around the mortgage, so the people you love can keep the place they already know. This is not lender-required insurance.
Offer not available in New York, New Jersey, or Pennsylvania.
The first step is a short questionnaire. No obligation to apply.
15 minutes
A weekday phone call
Eastern time
You pick an open slot
No obligation
You decide whether to apply
Home means more than a payment
It is the routines, the school run, and the place your family already knows.
Planned around the mortgage
Coverage amount and length can be discussed alongside what you still owe and how long you expect to owe it.
A benefit your family can use
The people you name receive the life insurance benefit. They decide how it helps with housing and other needs.
A term that can match the loan
Many of these policies are term life, chosen for a period that lines up with the years the mortgage is still a concern.
Reserve your review
Choose a time that works for you.
A 15-minute phone conversation. Weekdays only. All times are Eastern.
Everglade Legacy Advisors
15-minute phone review
Eastern
Pick an open weekday. The time is saved on the office calendar. No obligation to apply.
The home
Leave the home as the legacy.
The goal is simple: if income stops because someone dies, the people at home have a benefit they can use so the house does not have to be the first decision they make.
The benefit
A death benefit planned around the mortgage.
Coverage is life insurance sized for a housing need. It can help the people you name with the payment and other household costs.
A benefit your family can use for the home.
01
You choose the beneficiary
The life insurance benefit is paid to the people you name. They decide how it helps with the house and other household needs.
02
Amount and years
We look at the balance, the years left on the loan, and what else the family would still need. The policy does not promise the mortgage will be fully repaid.
03
Different from PMI
Lender-required mortgage insurance protects the lender. This conversation is about life insurance for your household.
How we shape the review
Step 1
Start with the house
Who lives there, what the payment means to them, and what you want them to be able to do.
Step 2
Match coverage to that picture
A benefit amount and a term that fit the years the mortgage is still the main concern. Copying the loan balance exactly is not always the right fit.
Step 3
See what applying involves
Health, age, and the carrier’s rules decide what is available. A review is not an approval, and losing a job does not trigger a life insurance payout.
Questions we settle in the review
How much
The remaining mortgage, other debts, and everyday costs — then a benefit that fits the budget.
How long
A term that covers the years the loan is still the main concern.
Who receives it
The beneficiary you choose, with a clear explanation of what the payout can and cannot do.
What you can understand in 15 minutes.
You complete a short questionnaire. If the office accepts it, you can choose a time with a licensed advisor. The conversation is about the home, a benefit amount and term to explore, and whether the cost fits. No obligation to apply.
- Your mortgage and household priorities.
- An appropriate coverage amount and duration to explore.
- Who receives the benefit and how applying works.
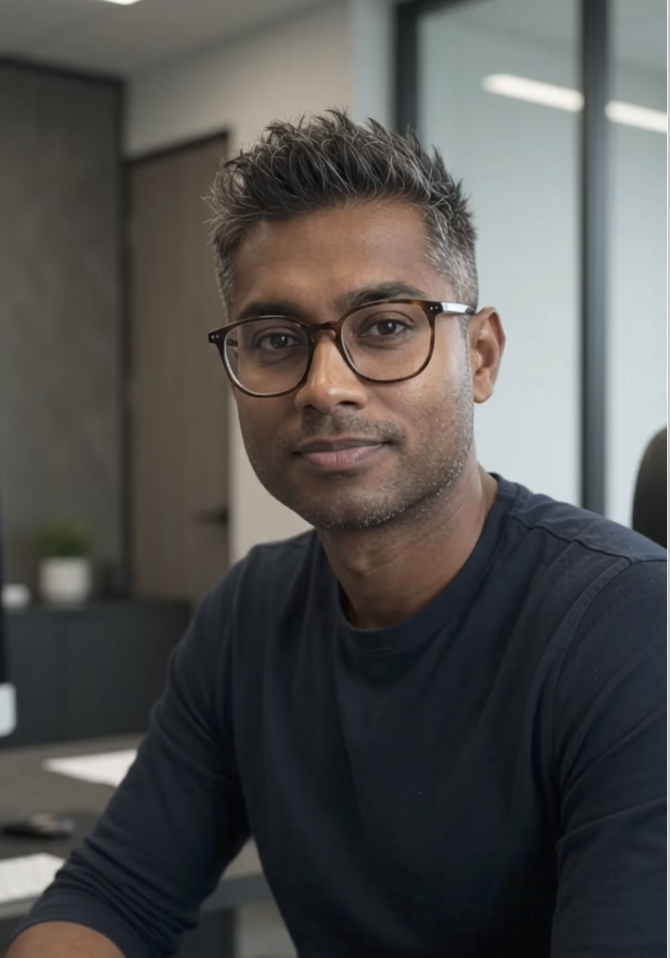
About Simon
A conversation with a real person.
Hi, I'm Simon. My goal is to help families create a legacy they can be proud of, protecting the people they love and building generational wealth.
When I'm not helping a family build a legacy, I'm outside with my dogs, on a trail, working on my own.
Plain language
Who you want to look after comes first.
Then we talk through the coverage worth exploring.
20128364
National Producer Number
Look it up before you book.
Verify
Check the license yourself.
Verify this licenseoffice@evergladelegacyadvisors.com407-476-8216Facebook
What happens next
1
Send a short request
Answer a few questions. If delivery fails, your answers stay on the page so you can try again.
2
Book only if you want to
After the office accepts the request, you can choose a 15-minute weekday phone call. Booking is optional.
3
Leave with a clear next step
Simon explains costs, limitations, and whether the policy is worth exploring. A request is not an application.
Questions people ask first
Does my lender require this?
No. This is optional life insurance for your family. It is separate from any insurance your lender requires.
If I lose my job, does the policy pay the mortgage?
No. These policies pay a death benefit. They are not unemployment or disability coverage.
Will the policy pay off the house automatically?
The benefit goes to your beneficiary. They can choose to put it toward the mortgage. The policy itself does not guarantee the loan will be fully repaid.
Is this the same as final expense or IUL?
No. This review is about term life planned around the home. Final expense and indexed universal life are different conversations.
What happens after I send my request?
If the office accepts it, you can choose a 15-minute weekday phone call. Booking is optional. A request is not an application and does not put coverage in force.
Start with a conversation, not an application.
Fifteen minutes. Your questions. No obligation to apply.