Indexed universal life insurance
Protection for your family. Potential to grow cash value — with guardrails.
An IUL is permanent life insurance. It is not a stock. It is not a 401(k).
Death benefit for the people who depend on you. Cash value that may be credited from a market index, typically with a 0% floor on those credits in down years. Living-benefit riders on many contracts.
Death benefit
Cash-value potential
Living-benefit riders
Free 15-minute review · No obligation · Licensed insurance professional
Why this exists
Term runs out. Markets drop. Medical bills show up while you are still here.
An IUL is one way some families combine a death benefit with the potential to accumulate cash value and, on some contracts, living benefits. It is not right for everyone. The next step is to see whether it even fits.
Why an IUL
Four jobs one policy can be designed to do.
Index-linked growth with a floor on credits
Cash value may be credited based on a market index — without investing in the market. In down years, indexed credits are typically floored (often 0%). Caps, participation rates, and spreads still apply.
Access later through policy loans
Many people use policy loans or withdrawals for supplemental retirement income. Loans are generally not income-taxable if the policy stays in force. A lapse with a loan can create a tax bill. This is not a 401(k) or IRA.
Living benefits for real-life emergencies
If a qualifying critical, chronic, or terminal illness rider is on the policy, you may accelerate part of the death benefit while living. Riders have definitions and limits. They are not a substitute for health or disability insurance.
Coverage that can last a lifetime
Unlike term that expires, an IUL is designed as permanent coverage if premiums are paid and the policy does not lapse. The death benefit typically passes to beneficiaries income-tax-free under current law.
How the cash value works
Linked to an index. Not invested in the index.
In stronger index years, interest credited to the cash value is limited by the cap or participation rate in your contract. In weaker years, that bucket typically does not take the index loss — and may credit 0%. Fees, cost of insurance, and loans still affect the account. Nothing here is a projection.
Not in the market
You do not own the stocks in the index. Indexed interest is a crediting method inside an insurance contract.
Flexible premiums (within limits)
You can often adjust premium and death benefit as income and goals change, subject to the contract and IRS rules (including MEC testing).
A different path than only a 401(k)
An IUL is not a replacement for employer retirement plans. Some households use it as an additional, insurance-based strategy after they understand the costs and tradeoffs.
A legacy, not just a number
The death benefit is for the people who depend on you — spouse, children, or a business — not a savings slogan.
Free 15-minute review · No obligation · Licensed insurance professional
Advisor
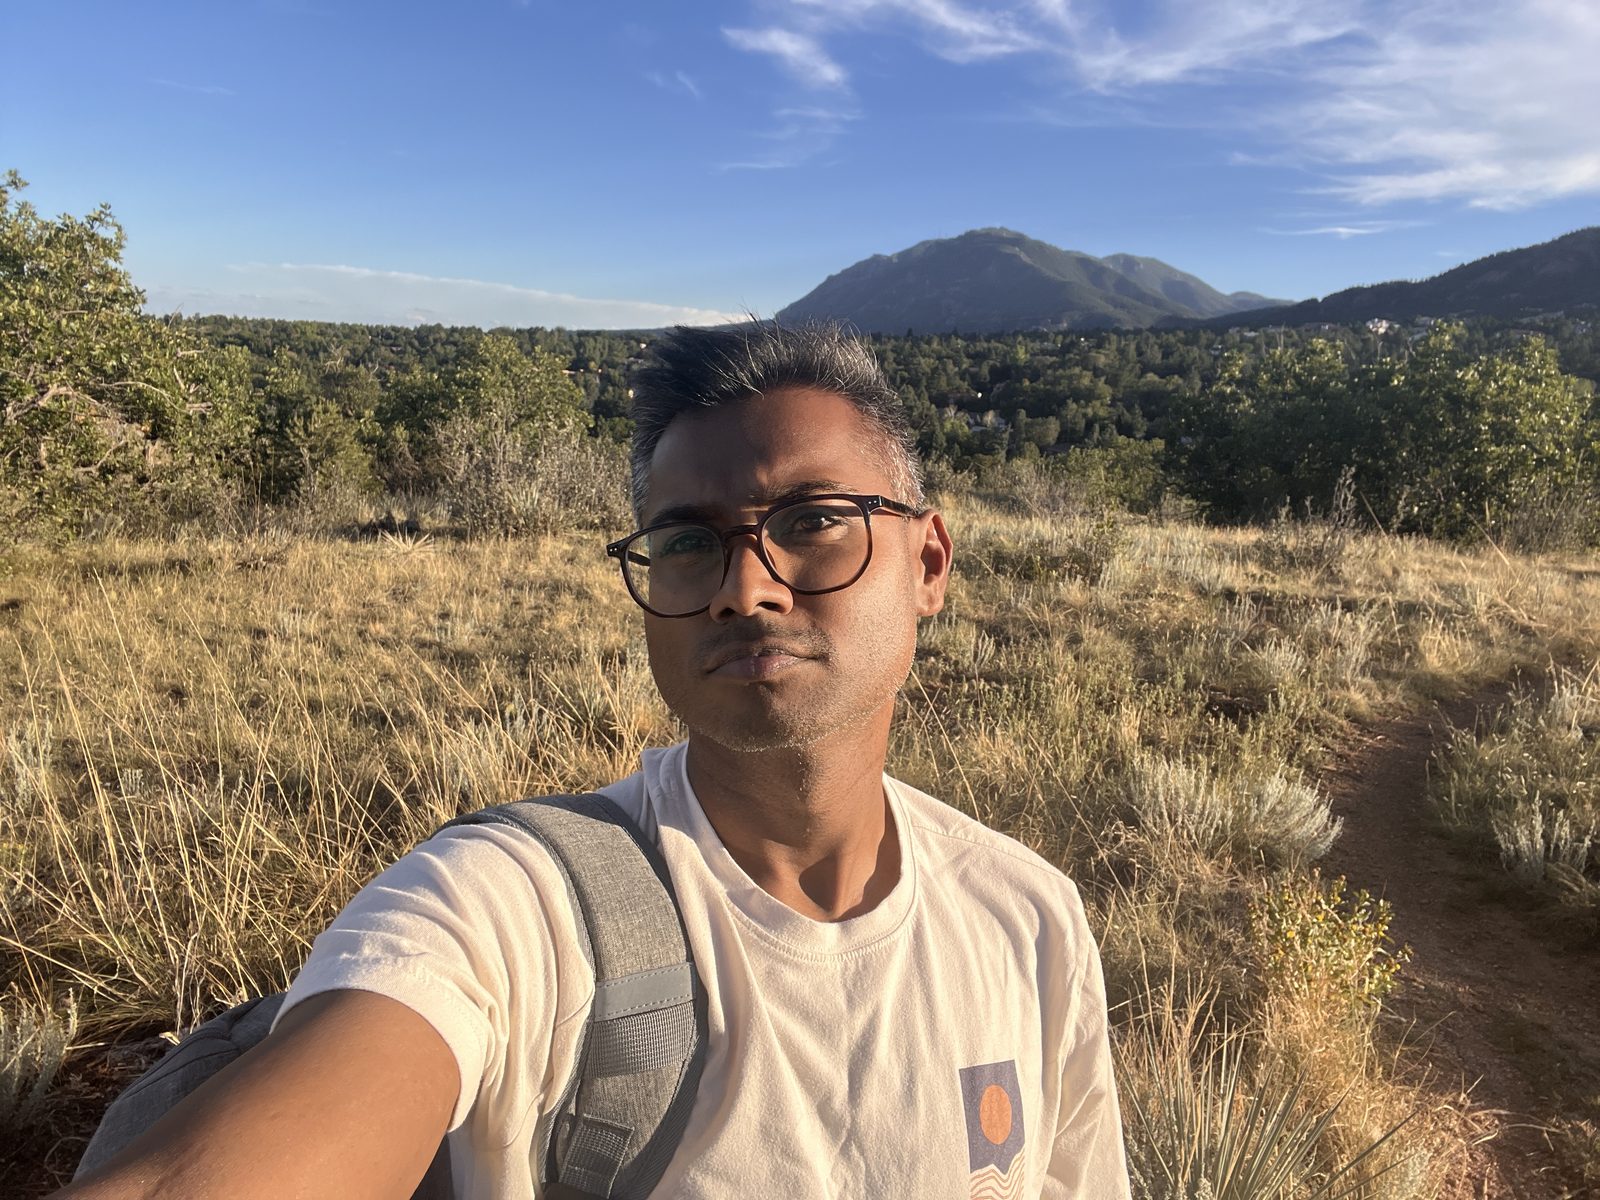
Simon Pullay
Independent insurance professional · Everglade Legacy Advisors · NPN 20128364
I grew up in a house that treated hard work and looking after other people as the same job. I help families see whether an IUL, term, final expense, or something else actually fits — and I will say so if it does not.
Free 15-minute review · No obligation
FAQ
Straight answers.
No. It is a life insurance contract. Indexed interest may be linked to an index. You do not invest directly in that index. It is not a security and not FDIC insured.
See if an IUL even belongs in the plan.
Answer a few questions. Book 15 minutes. If it is not a fit, you leave knowing that.
Free 15-minute review · No obligation · Licensed insurance professional